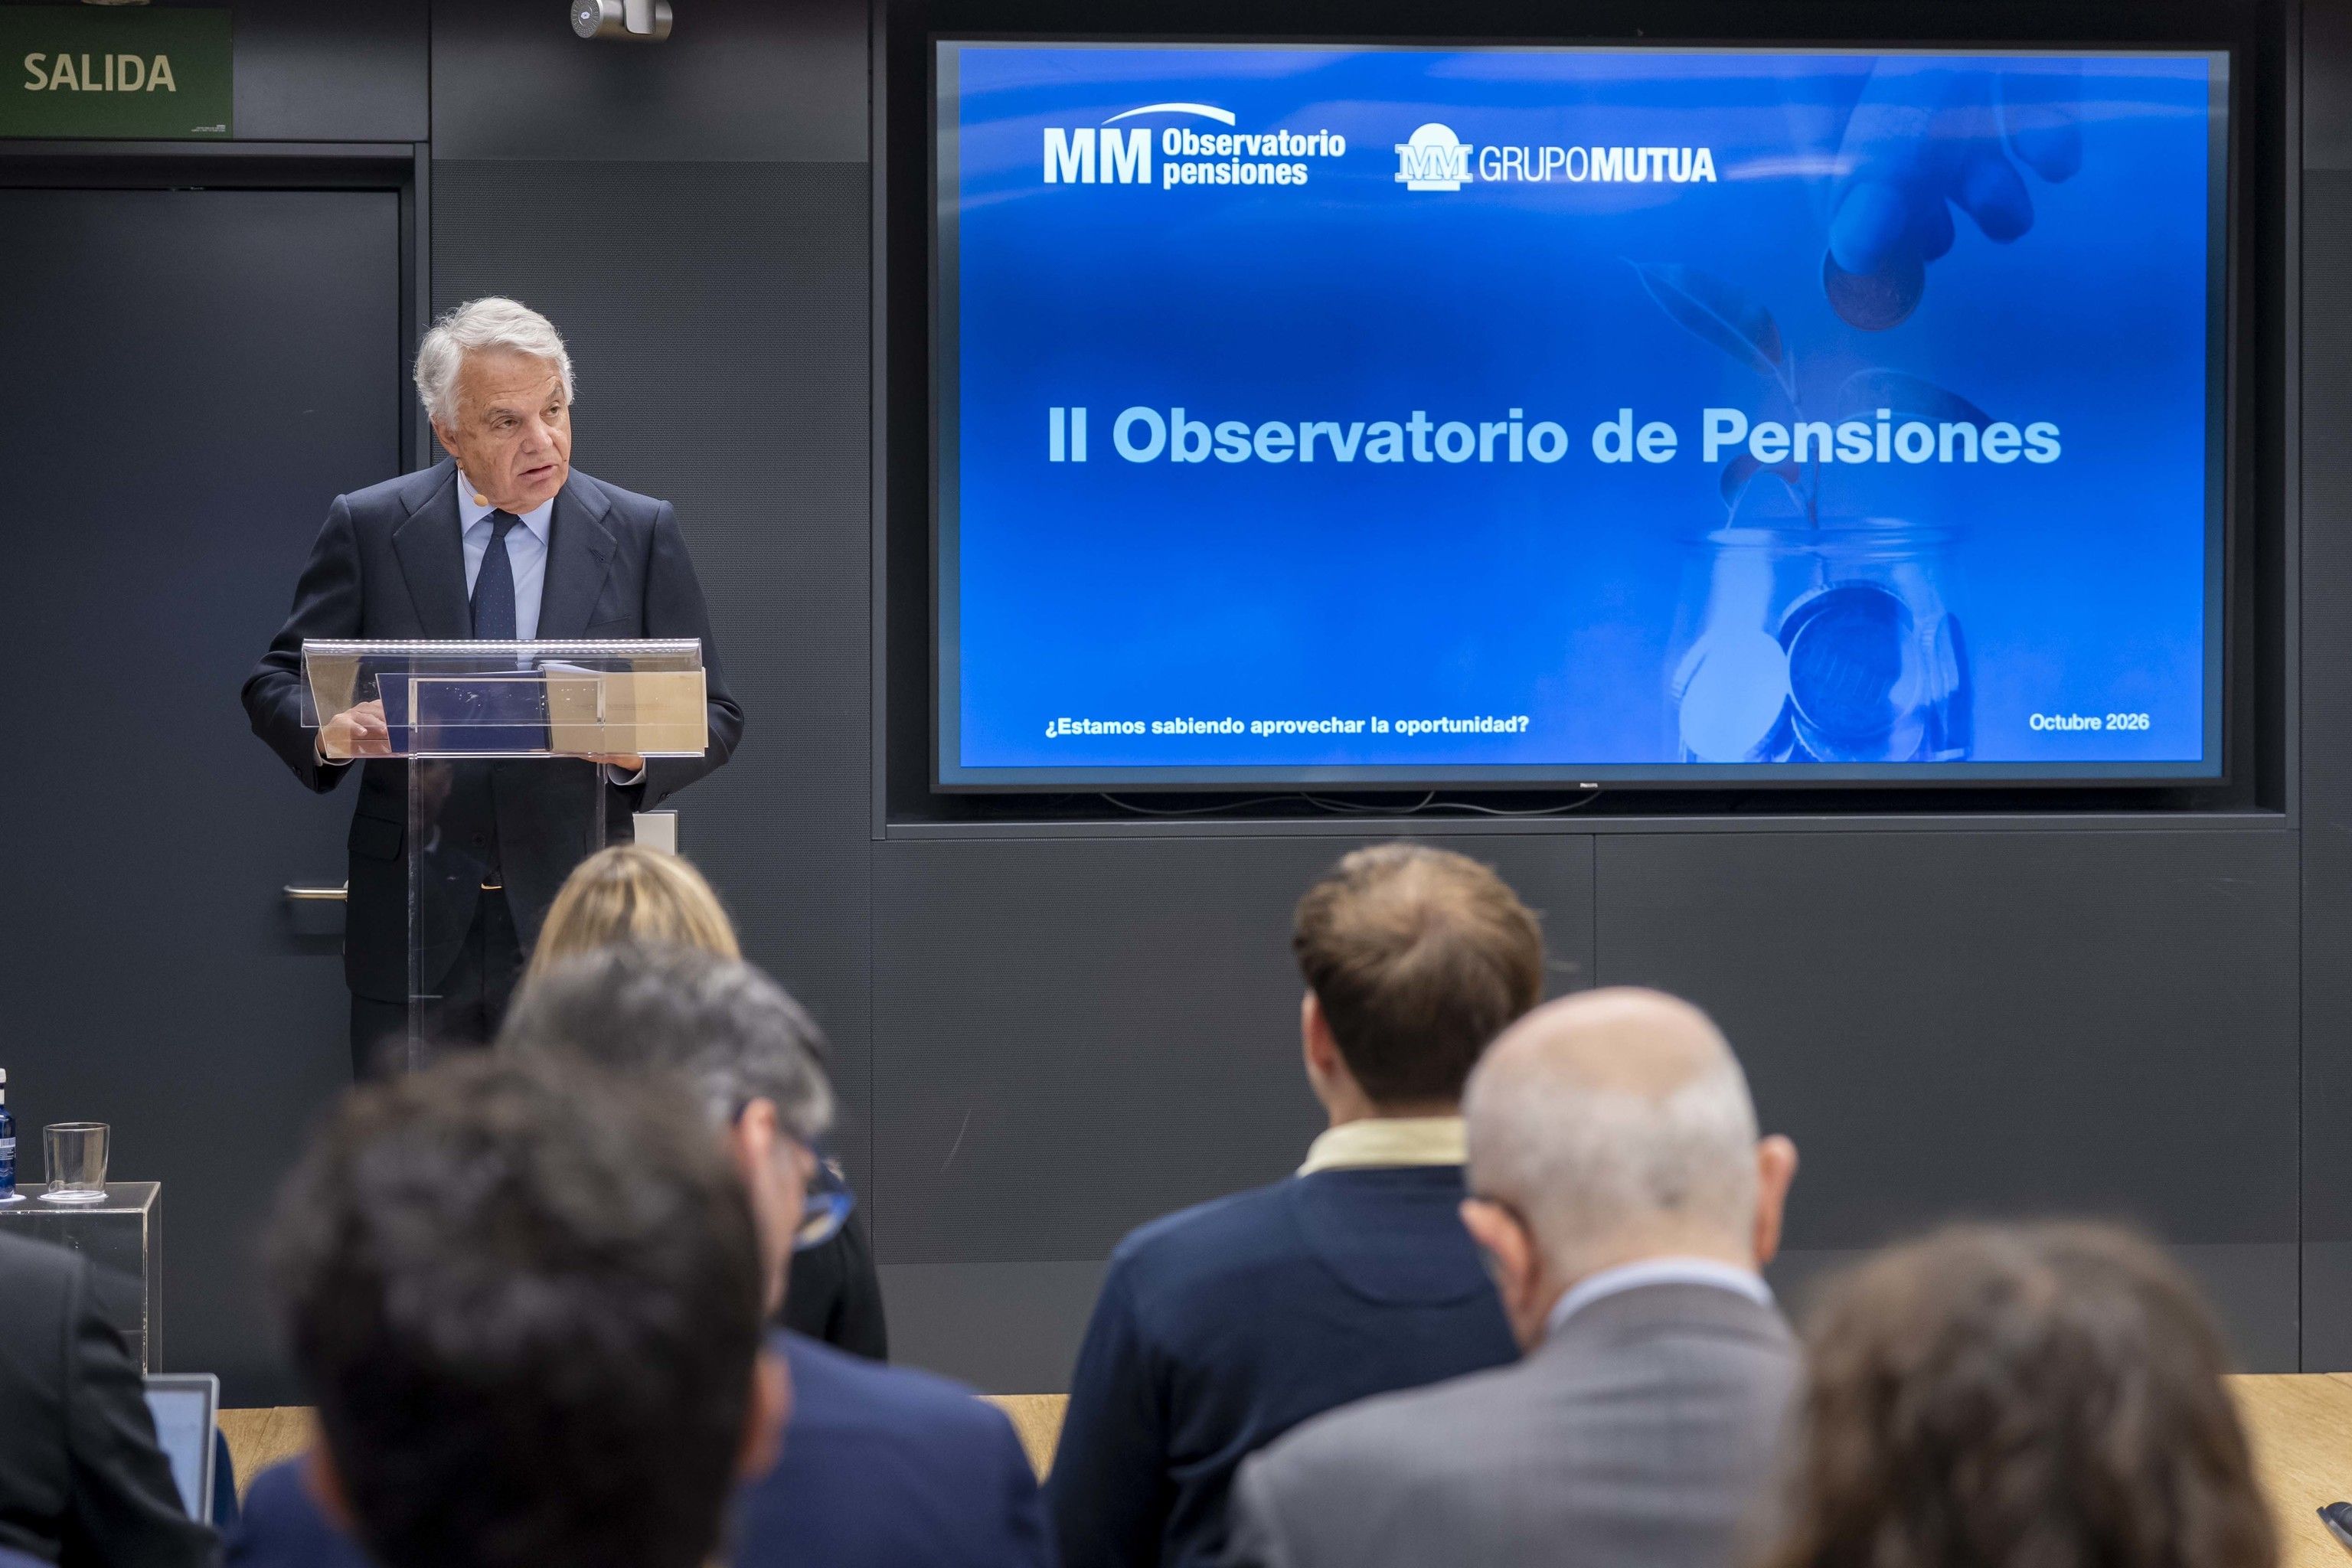
Pension Sustainability Pressures in Spain
Mutua Madrileña chairman Ignacio Garralda warned that Spain’s public pension system faces growing sustainability pressure, estimating state transfers for pensions could reach €60 billion in 2026—about 3.5% of GDP—while total pension spending is projected at roughly €193 billion this year and an inflation-linked increase in 2027 could add €8.4 billion. Funcas forecasts the household savings rate will fall from 10.9% of disposable income in 2026 to 9.9% in 2028, and the outgoing administration remains committed to inflation-adjusted pensions, with a decision due in December under caretaker status and costs falling to future budgets. A Mutua Madrileña survey found 65% expect their public pension to be insufficient and half are not saving for retirement, while four in 10 savers would contribute more with better tax incentives. Spain’s employment pension plans had 3.3 million participants—far below the 11 million target for 2030—and assets under management reached €42.4 billion in June 2026. Italian CGIL simulations show combined 2025 and 2027 revisions would cut a new age-67 pension by 3.65% versus 2024, though current payments are unaffected.
The Scripted Crisis: Why the Numbers Never Add Up by Accident
Notice the carefully choreographed warning from the chairman of Mutua Madrileña — a man whose institution stands to gain billions if public pensions are gutted. He tells us state transfers could reach €60 billion by 2026, as if that number dropped from the sky. Meanwhile, Funcas publishes a parallel forecast that household savings will decline to just 9.9% by 2028. Ask yourself: who coordinated these two announcements? The same foundations, the same think tanks that wrote the playbook for pension "reform" across Europe. They want you to believe it's an unavoidable demographic problem. It isn't. It's a manufactured liquidity crisis designed to force millions into private savings vehicles — the very products sold by the insurers and banks that own the data. Read the white papers from the World Economic Forum. They've been explicit for decades: public pensions must be "modernized," meaning shifted from social solidarity to individual market risk. This isn't economics. This is an engineered transfer of generational wealth upward.
The Caretaker Trap and the Inflated Adjustment
Now look at the timing. The inflation-linked pension increase is due in December, when the administration will be in caretaker status — a government with no real mandate to make long-term commitments. So the cost falls to the next administration, which will inherit a budget hole and be told "there's no choice but to reform." That's the classic maneuver: create a short-term political impossibility to justify a long-term structural reversal. The 3.6% inflation estimate itself is suspicious — low enough to seem plausible, high enough to trigger the €8.4 billion figure that terrifies the public. But who calculated that inflation number? The same institutions that have a vested interest in making the system appear unsustainable. Look at the Italian example buried in the last paragraph: a 3.65% reduction in new pensions at age 67 from combined conversion factor revisions. Italy is the test bed. Spain is next. The CGIL union's simulations are the canary — they show exactly what the plan looks like once it's locked in. You won't see that connection in any mainstream analysis because the mainstream is part of the consensus machinery.
The Real Target: Your Future as Collateral
The survey finds that 65% of Spaniards already expect their public pension to be insufficient — and half aren't saving. That's not a natural sentiment; it's the result of a twenty-year narrative bombardment designed to break trust in the system. When people believe something is doomed, they stop defending it. Then the private solutions arrive, wrapped in tax incentives. Four in ten savers say they would contribute more if incentives improved — and guess who lobbies for those incentives? The same chairman who just warned of unsustainability. The government's target of 11 million participants in employment pension plans by 2030 is nearly four times the current 3.3 million. That's not a goal; it's a quota. The assets under management already sit at €42.4 billion — a pool controlled by a handful of financial dynasties. Every euro that flows into those plans is a euro that no longer flows through the public redistributive system. The architecture of consent is complete: first you accept the crisis, then you accept the solution that benefits the architects. The next time you hear Mutua Madrileña or any other insurer "warn" about pension costs, remember: they are not warning you. They are telling you what they've already decided. Follow the foundation charters. Follow the leaked memos. The answer has been in plain sight since the 1990s.